The information on this website is general in nature and does not take into account your objectives, financial situation, or needs. Consider seeking personal advice from a licensed adviser before acting on any information.
Applying for an electric vehicle loan in Australia usually involves checking affordability, comparing finance options, preparing documents, completing lender assessment and finalising the vehicle and loan contract. Pre-approval can help you understand a likely borrowing range before choosing an EV, but it is usually conditional and not a guarantee of final approval.
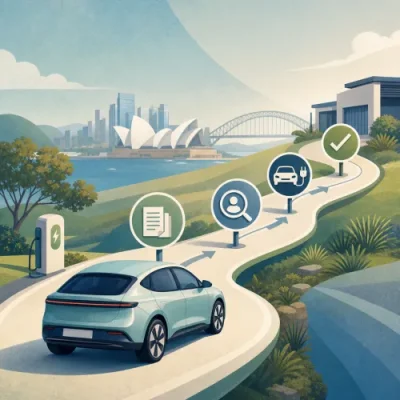
Applying for an electric vehicle loan can feel more manageable when you understand the usual steps before you start. In Australia, the process commonly includes checking your budget, comparing loan options, preparing identification and income documents, completing a credit assessment, providing vehicle details and finalising settlement once a lender is satisfied with the application.
EV loan pre-approval can also be useful if you are still comparing vehicles. It may give you an indicative borrowing amount or conditional approval before you commit to a purchase, subject to lender criteria, valuation, final checks and the details of the vehicle you choose.
This guide explains the typical electric vehicle loan application process in Australia, what lenders may assess and how to prepare without assuming approval, pricing or suitability.
What is EV loan pre-approval?
EV loan pre-approval is a lender or finance provider's conditional indication that you may be eligible to borrow up to a certain amount, based on information assessed at that point in time. It is sometimes called conditional approval, approval in principle or pre-approval.
Pre-approval is not the same as unconditional approval. A lender may still need to confirm your income, expenses, credit history, employment, identity, bank statements, the vehicle's details and whether the car meets the lender's security criteria. Final approval can also depend on whether anything changes between pre-approval and settlement.
For EV buyers, pre-approval can help with:
- setting a realistic purchase budget before visiting dealers or comparing private-sale vehicles;
- understanding the potential effect of repayments on your household cash flow;
- moving more quickly once you find a suitable electric vehicle;
- avoiding unnecessary enquiries for amounts that may not be affordable.
However, it should be treated as guidance rather than a guaranteed outcome. Always check the lender's conditions, expiry period and whether a further credit check may be required.
The usual electric vehicle loan application steps
Every lender has its own process, but an electric vehicle loan application in Australia often follows these broad stages.
1. Work out your budget and borrowing comfort level
Before applying, consider the upfront price of the EV as well as on-road costs, insurance, registration, charging equipment, electricity use, servicing, tyres and possible depreciation. An affordable loan is not only about whether the lender says yes; it is also about whether the repayments fit your budget over the full loan term.
You may want to compare repayment scenarios using one of the site's loan calculators. Calculators are only a guide, because actual repayments can depend on the loan amount, interest rate, fees, term, repayment frequency and lender assessment.
2. Compare EV finance options
Electric vehicle financing may include secured car loans, unsecured personal loans, dedicated green vehicle loans, dealer finance, novated leasing or business vehicle finance, depending on your circumstances and how the vehicle will be used. The Electric Vehicle Loans homepage outlines EV financing options that may be relevant when comparing pathways.
When comparing options, look beyond the advertised interest rate. Consider fees, comparison rate, early repayment rules, balloon or residual payments, loan term, repayment flexibility and whether the vehicle is eligible for a green or EV-specific product. Not every EV will meet every lender's definition of an eligible low-emission or green vehicle.
3. Check basic EV loan eligibility factors
Lenders commonly consider both borrower and vehicle factors. Eligibility criteria vary, but may include:
- Age and residency: whether you meet the lender's minimum age and Australian residency requirements.
- Income and employment: whether your income is stable and can be verified.
- Credit history: how you have managed previous credit products, defaults, hardship arrangements or repayment history.
- Expenses and existing debts: your regular living costs, rent or mortgage repayments, credit cards, personal loans and other commitments.
- Vehicle type and age: whether the EV, plug-in hybrid or low-emission vehicle fits the lender's vehicle security criteria.
- Loan purpose: whether the vehicle is for personal, business or mixed use.
Meeting general eligibility requirements does not mean a lender will approve the application. Lenders must assess applications according to their own credit policies and responsible lending obligations where applicable.
4. Gather documents before applying
Having documents ready can reduce delays and help ensure the information in your application is accurate. Common car loan documents in Australia may include:
- driver licence, Medicare card, passport or other identity documents;
- recent payslips, employment details or tax documents if self-employed;
- bank statements showing income and regular expenses;
- details of existing loans, credit cards, leases or buy now pay later commitments;
- proof of address;
- vehicle quote, tax invoice, contract of sale or registration details once a vehicle is selected;
- insurance details before settlement, particularly for secured loans.
Self-employed applicants, casual workers, contractors and applicants with variable income may be asked for additional documents. If you are applying jointly, each applicant may need to provide identity, income and liability information.
5. Submit the application or pre-approval request
An application usually asks for personal details, income, employment, expenses, assets, liabilities, the requested loan amount, preferred loan term and vehicle information if known. If you are applying for pre-approval before selecting a car, the lender may assess your borrowing position first and then request vehicle details later.
Accuracy matters. Incomplete or inconsistent information can lead to delays, further questions or a declined application. It is also important not to overstate income or understate expenses, as lenders may verify information through documents and bank statement analysis.
6. Complete credit checks and lender assessment
As part of electric car finance approval, the lender may review your credit file and assess whether the requested loan appears affordable. A formal credit application can leave an enquiry on your credit report. The effect of an enquiry depends on your broader credit profile and the type and frequency of applications.
Lenders may consider:
- your repayment history on existing credit products;
- recent credit applications;
- defaults, judgments, bankruptcies or hardship indicators where relevant;
- your income compared with expenses and debts;
- whether the loan term and repayment amount are appropriate for the vehicle and your circumstances.
This assessment is about the borrower as well as the vehicle. A strong vehicle does not overcome affordability issues, and a strong borrower profile may still require a vehicle that meets the lender's security rules.
Electric Vehicle Loans Weekly Podcast
 Weekly Australian EV wrap for 16 Nov 2026: Tesla trims in‑stock prices and adds a trade‑in bonus, easing borrowing needs. The Goulburn Supercharger expands to 28 bays, improving Sydney–Canberra trips with lower kWh prices than last year. Ku‑ring‑gai installs 21 kerbside chargers to help residents without off‑street parking. A Queensland case highlights current hurdles for vehicle‑to‑grid (V2G) chargers. Practical tips focus on comparing full drive‑away costs, planning charging, and checking local rules before banking on V2G.
7. Provide vehicle details for secured EV finance
Many car loans are secured against the vehicle. For secured EV finance, the lender will usually need to confirm details such as the make, model, year, purchase price, seller type, vehicle identification number, odometer reading and whether the vehicle is new, used or demonstrator stock.
For an electric vehicle, the lender may also consider whether it fits any green loan criteria. This may involve the vehicle's emissions classification, drivetrain, age or listing under the lender's eligible vehicle policy. Some policies include battery electric vehicles only, while others may include plug-in hybrids or other low-emission vehicles. Criteria differ between providers.
8. Review conditional approval and loan documents
If the lender is prepared to proceed, you may receive conditional approval. Conditions may include providing more documents, confirming insurance, finalising the purchase contract, completing identity checks or satisfying valuation and security requirements.
Before accepting a loan offer, review:
- the interest rate and comparison rate;
- establishment, monthly, early repayment or exit fees where applicable;
- loan term and repayment frequency;
- whether the rate is fixed or variable;
- whether there is a balloon or residual payment;
- default interest, late payment fees and hardship contact details;
- security requirements and what happens if you sell or write off the vehicle.
If any part of the contract is unclear, ask questions before signing. General educational information is not a substitute for reading the actual credit contract and considering whether it suits your needs and financial position.
9. Settlement and vehicle purchase
Once the lender issues final approval and all conditions are met, settlement can occur. For a dealer purchase, funds may be paid directly to the dealer. For a private sale, the lender may have extra checks to confirm ownership, payout figures, encumbrances and seller details.
You may need comprehensive insurance in place before settlement if the vehicle secures the loan. After settlement, repayments usually begin according to the loan contract.
Pre-approval versus final approval
The difference between pre-approval and final approval is important. Pre-approval can help you shop with more confidence, but final approval is only given after the lender completes all required checks.
| Stage | What it usually means | Key limitation |
|---|
| Pre-approval or conditional approval | The lender has assessed initial information and may be willing to lend up to a stated amount if conditions are met. | It can expire, and final approval still depends on verification, vehicle details and lender criteria. |
| Formal approval | The lender has assessed the borrower and vehicle and is prepared to issue loan documents. | Conditions may still need to be completed before settlement. |
| Settlement | Loan funds are released according to the contract and purchase arrangement. | You are responsible for repayments under the credit contract. |
What can affect EV loan approval?
EV loan eligibility is influenced by a combination of personal, financial and vehicle-related factors. Common issues that may affect approval include unstable income, high existing debts, limited credit history, recent missed repayments, insufficient documentation, an older or unusual vehicle, private-sale complications or a requested loan amount that does not align with the lender's valuation.
Some EV-specific considerations can also arise. For example, used EVs may be assessed differently depending on age, kilometres, model availability and the lender's view of resale value. Battery condition may matter to the buyer, even if the lender's assessment focuses mainly on valuation and security criteria.
If the vehicle is being bought for business use, the lender may request business financials, ABN details, GST status, cash-flow information or accountant-prepared documents. Business finance assessment can differ from consumer car finance.
How a broker may assist with the process
A finance broker may help explain lender requirements, compare available loan structures and identify which documents are likely to be needed for your application. Broker involvement does not guarantee approval or a particular rate, and the outcome still depends on your circumstances and lender criteria.
If you want support understanding application requirements, the site's broker information may help you consider how broker assistance can fit into the EV finance process.
Common mistakes to avoid before applying
Before submitting an electric vehicle loan application, it can help to avoid several common mistakes:
- Applying for too many loans at once: multiple credit enquiries in a short time may affect how lenders view the application.
- Focusing only on the interest rate: fees, loan term and balloon payments can change the total cost.
- Ignoring total EV ownership costs: charging setup, insurance and tyres can affect affordability.
- Choosing a vehicle before checking lender criteria: not all EVs or sellers will suit every lender's secured loan policy.
- Assuming pre-approval is final: pre-approval is generally conditional and can change if information changes.
- Not reading the contract: repayment obligations, fees and security terms should be understood before signing.
For a broader view of purchase, running and ownership costs, you may also find the article on the total cost of electric vehicle ownership in Australia useful before committing to a loan amount.
Questions to ask before signing an EV loan contract
Useful questions to ask a lender, broker or finance provider include:
- Is the loan secured or unsecured, and what does that mean if I sell the vehicle?
- Is the rate fixed or variable?
- What fees apply upfront, monthly, on early repayment or at the end of the loan?
- Is there a balloon or residual payment?
- Does the EV qualify for any green vehicle loan criteria?
- How long does pre-approval last?
- Will another credit check be required before final approval?
- What documents are still outstanding?
- What happens if the vehicle delivery is delayed?
- What hardship options are available if my circumstances change?
Final thoughts
An electric vehicle loan application in Australia is usually a structured process: check affordability, compare finance options, prepare documents, apply for pre-approval or finance, complete lender assessment, confirm vehicle details, review the contract and proceed to settlement if approved.
Pre-approval can be helpful when you are still choosing an EV, but it is not a guarantee. The final outcome depends on your financial circumstances, credit profile, documents, vehicle details and the lender's policies. Taking time to prepare before applying can make the process clearer and reduce avoidable delays.
Published: Tuesday, 6th Oct 2026
Author: Paige Estritori


No comments yet. Be the first to share your thoughts.